


How Long Distance Retirement Moves Work: 2026 Guide
A long-distance retirement move is a specialized relocation requiring coordinated logistics, financial planning, and lifestyle adaptation that goes well beyond what a typical local move demands. Understanding how long distance retirement moves work means grasping three distinct layers: the operational mechanics of how movers schedule and deliver your belongings, the full financial picture of your new location, and the practical steps for settling into a new community. Retirees who treat this as a simple “pack and go” process often face unexpected costs, delayed deliveries, and stressful transitions. The good news is that with the right preparation, this move can be one of the most rewarding decisions of your retirement.
How do delivery windows and logistics affect long-distance retirement moves?
Long-distance retirement relocation operates on a fundamentally different schedule than a local move. Delivery windows span several days or more because moving companies route trucks across multiple customer stops, not just yours. This means your furniture and boxes may arrive anywhere within a three to fourteen day range after pickup, depending on the route, driver hours, and how many other households share that truck.
This shared routing model exists for a practical reason. Trucks serve multiple customers on the same route, and consolidating shipments keeps costs lower for everyone. The trade-off is flexibility on your end. If you demand an exact delivery date, you will typically pay a premium for expedited or priority service.
Here is what drives delivery window timing:
- Route sequencing: Your stop is one of several, and the order depends on geography, not your preference.
- Driver hours: Federal regulations cap how many hours a commercial driver can operate per day, which affects how quickly a truck moves across states.
- Multiple pickups and drops: A truck heading from Massachusetts to Florida may stop in Connecticut, New Jersey, and Georgia before reaching you.
- Weather and road conditions: Delays outside the mover’s control can push windows back further.
Requesting earliest available delivery in writing is one of the most effective ways to reduce uncertainty. Verbal agreements mean nothing in this context. The commitment must appear in your contract, specifically in the bill of lading or order for service, to be enforceable.
Pro Tip: Ask your mover to note “first available delivery” directly on the bill of lading before you sign anything. This single step gives you legal standing if your belongings arrive later than discussed.
If your destination is not ready to receive delivery, you face storage-in-transit costs, where your belongings sit in a warehouse at your expense until you can accept them. Planning your move-in date with at least a two to three day buffer before the earliest delivery window closes is a smart way to avoid this scenario.
What financial considerations should retirees evaluate beyond moving costs?
The upfront cost of hiring long-distance movers is only one piece of the financial picture. Retirees often underestimate the ongoing costs of living in a new location, and that gap between expectation and reality can strain a fixed income quickly.
Evaluating retirement income against ongoing costs like property taxes, healthcare, and long-term care is the correct starting point, not just comparing state income tax rates. A state with zero income tax may offset that advantage with high property taxes, elevated sales taxes, or limited Medicaid coverage for long-term care facilities.
Consider these cost categories before committing to a destination:
- Property taxes: Florida and Texas have no state income tax but carry property tax rates that can significantly affect retirees on fixed incomes.
- Healthcare access and cost: Rural retirement destinations may offer lower housing costs but limited specialist access, which drives up out-of-pocket medical expenses.
- Long-term care planning: Assisted living and memory care costs vary dramatically by state. In Massachusetts, the median annual cost for assisted living exceeds the national average.
- Sales tax on essentials: Some states tax groceries and medications, which adds up over years of retirement spending.
- Cost of living index: Housing, utilities, and transportation costs compound over a 20 to 30 year retirement horizon.
“Retirees should work backwards from their monthly income and model what their actual take-home spending looks like in the new location, not just what they save on taxes.” — Fidelity Investments
The moving costs by distance are a one-time expense. The ongoing cost of living in the wrong location is a permanent one. Consulting a fee-only financial advisor or a CPA familiar with multi-state tax issues before finalizing your destination is one of the highest-return steps you can take in this process.
What challenges do retirees commonly face during long-distance moves?
Long-distance retirement relocation surfaces challenges that younger movers rarely encounter. Downsizing is the most emotionally loaded of these. Decades of accumulated belongings must be sorted, donated, sold, or discarded, and that process takes longer than most people expect.
Here is a practical sequence for managing the most common challenges:
- Start downsizing 90 days out. Go room by room and categorize items into keep, donate, sell, and discard. Estate sale companies like EstateSales.net can help move large volumes of furniture and collectibles quickly.
- Align your lease or home sale closing with your move date. Gaps between leaving your current home and arriving at your new one create costly temporary housing needs.
- Confirm building and community regulations at your destination. Many retirement communities and condominiums have specific move-in hours, elevator reservations, and restrictions on large trucks. Failing to check these details can delay your delivery.
- Coordinate family support early. If adult children or friends are helping, lock in their availability at least six weeks before the move. Last-minute schedule changes are one of the most common sources of moving day stress.
- Plan for storage-in-transit. If your new home is not ready when your truck arrives, storage-in-transit risks include additional fees and the possibility of your belongings being unloaded and reloaded, which increases the chance of damage.
Pro Tip: If you are moving into a 55-plus community or a high-rise, call the building manager four to six weeks before your move to reserve the freight elevator and confirm move-in window hours. Missing this step can cost you an entire day.
The emotional side of downsizing deserves direct acknowledgment. Letting go of a family home or possessions tied to decades of memories is genuinely difficult. Giving yourself permission to take that process slowly, and to involve family members in meaningful decisions about heirlooms, makes the transition healthier for everyone involved.
How can retirees plan and execute a successful long-distance retirement relocation?
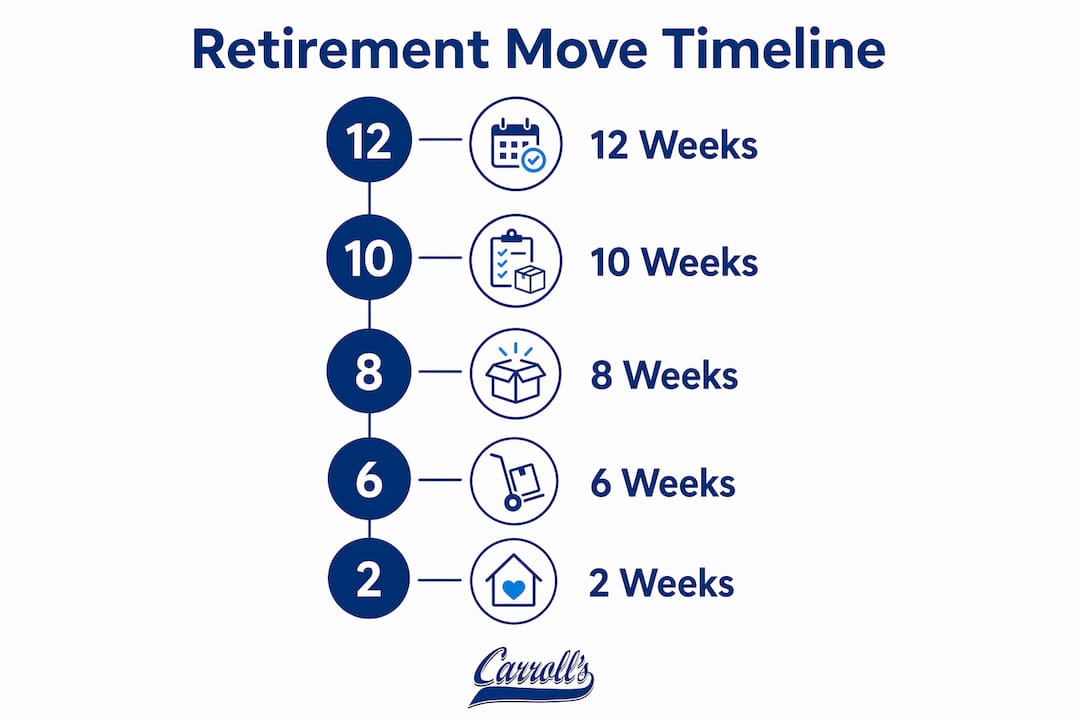
Successful planning retirement moves follows a clear timeline. Starting at least two to three months before your target move date gives you enough runway to make good decisions without rushing.
| Timeframe | Action |
|---|---|
| 10-12 weeks out | Research and request quotes from at least three licensed movers |
| 8-10 weeks out | Confirm binding estimate, sign contract, begin downsizing |
| 6-8 weeks out | Notify utilities, healthcare providers, and financial institutions of address change |
| 4-6 weeks out | Begin packing non-essentials; arrange storage if needed |
| 2-4 weeks out | Confirm delivery window in writing; pack essentials bag for travel |
| Moving week | Do final walkthrough, transfer vehicle registration, update voter registration |
Early planning of two to three months or more allows retirees to declutter, coordinate family help, and align utilities and healthcare at the destination. Rushing this timeline is the single most common cause of avoidable moving problems.
When choosing a mover, verify that the company is licensed by the FMCSA and look up their Department of Transportation number in the federal database before signing anything. Unlicensed movers have no regulatory accountability, and disputes become extremely difficult to resolve.
On estimates: binding estimates lock in your total cost regardless of shipment weight variations, while non-binding estimates can increase if your actual load exceeds the quote. For retirees on fixed incomes, a binding estimate removes financial uncertainty from the equation.
Additional steps that matter:
- Set up healthcare providers at your destination before you arrive, not after. Finding a new primary care physician, cardiologist, or specialist can take weeks in some markets.
- Transfer prescriptions to a pharmacy near your new address at least two weeks before moving.
- Review your full-service move options to understand whether packing, unpacking, and furniture placement services are worth the added cost for your situation.
- Update your estate planning documents, including your will, power of attorney, and healthcare directive, to reflect your new state’s legal requirements.
Key takeaways
Successful long-distance retirement relocation requires understanding delivery windows, evaluating total ongoing costs at the destination, and following a structured planning timeline starting at least two to three months before moving day.
| Point | Details |
|---|---|
| Delivery windows are date ranges | Movers schedule deliveries across multiple stops; request earliest delivery in writing on the contract. |
| Total cost goes beyond moving fees | Evaluate property taxes, healthcare, and long-term care costs at your destination, not just income tax rates. |
| Downsizing takes longer than expected | Start 90 days out and go room by room to avoid last-minute decisions under pressure. |
| Licensing matters when choosing movers | Verify FMCSA licensure via the DOT database before signing any contract or paying a deposit. |
| Binding estimates protect fixed incomes | A binding estimate locks your total cost regardless of weight, removing financial uncertainty from the move. |
What I have learned from watching retirees navigate long-distance moves
After years of working in and around the moving industry on Cape Cod, the pattern I see most often is this: retirees who struggle with long-distance moves almost always underestimated one of two things. Either they underestimated how long the logistics would take, or they underestimated how much their new location would actually cost to live in month to month.
The delivery window issue surprises people every time. You spend weeks packing and planning, and then you learn your belongings might arrive on any one of seven days. That is not a failure of your mover. It is simply how long-haul trucking works. The retirees who handle it best are the ones who build flexibility into their schedule and keep a bag packed with essentials for the first week.
On the financial side, I have seen people move to states with no income tax and end up spending more overall because they did not model their full cost of living. The tax savings were real. The surprise property tax bill and the cost of driving 45 minutes to a specialist were also real.
What I find genuinely encouraging is how well retirees do when they give themselves enough time and ask the right questions early. The freedom that comes with choosing exactly where you want to live in retirement is real and worth pursuing. You just need the right information before you commit.
— Michael
How Carrollsmv can support your retirement relocation
Planning a long-distance retirement move from Cape Cod or Martha’s Vineyard takes more than a good checklist. It takes a moving partner with the experience to handle the details you cannot afford to get wrong.
Carrollsmv has served Cape Cod families for over 95 years, with an 80% repeat customer rate that reflects genuine trust built over generations. For retirees, that means access to white glove moving services for valuable or fragile belongings, flexible self-storage solutions when your move-in date and delivery window do not align perfectly, and a licensed, professional team that communicates clearly at every step. Whether you are relocating across state lines or across the country, Carrollsmv provides the scheduling flexibility and care that retirement moves demand. Contact Carrollsmv for a free moving estimate and start your relocation with confidence.
FAQ
What is a delivery window in a long-distance move?
A delivery window is a date range, not a fixed day, during which your moving company expects to deliver your belongings. Delivery windows are routing tools set after pickup is confirmed, based on route sequencing and driver schedules across multiple customer stops.
How do I protect myself from unexpected cost increases?
Request a binding estimate from your mover before signing any contract. Binding estimates lock in total cost regardless of actual shipment weight, which protects retirees on fixed incomes from surprise charges at delivery.
How far in advance should I start planning a retirement move?
Starting two to three months out gives you enough time to research movers, downsize, notify healthcare providers, and coordinate utilities at your destination without making rushed decisions.
Should I choose a state with no income tax for retirement?
Not automatically. Low income tax states may carry higher property taxes, elevated sales taxes, and limited long-term care coverage that offset the savings. Model your full monthly cost of living before committing to a location.
How do I verify that a moving company is legitimate?
Moving companies must be licensed by FMCSA, and you can verify any company’s Department of Transportation number through the federal FMCSA database before signing a contract or paying a deposit.
